What a Loan Closing Survey Can Reveal
A survey rarely gets much attention at the closing table until it shows a neighbor’s garage sitting two feet onto the lot you’re buying. A loan closing survey is a survey done during a purchase or refinance to show the property lines, buildings, and visible features for the lender and title company. Most come back without major surprises. When something does show up, you want to find it with enough time to deal with it, so read the survey yourself instead of assuming someone else caught every detail.
Property Boundaries and Improvements Shown at Closing
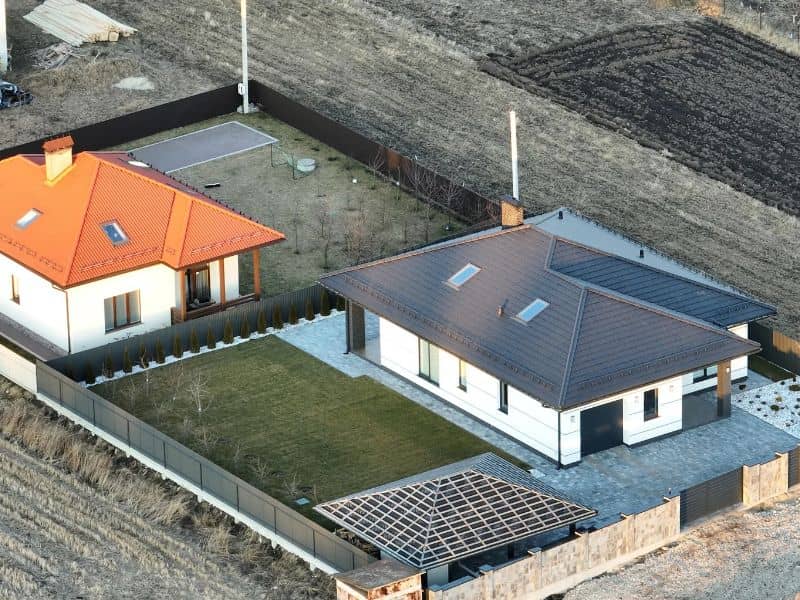
A loan closing survey shows where the property lines run and what sits inside them. Surveyors call anything built or added to the land an improvement. That includes the house, garage, driveway, fences, sheds, pools, and patios.
The property lines are usually drawn with bearings and distances. A bearing is the direction a line runs, and the distance is how long it is. Together they trace the shape of the lot, and they should match the legal description in the deed. If the numbers on the survey don’t line up with the deed, ask the surveyor about it.
Scope can vary by lender, title company, and surveyor. Some closing surveys are more limited than a full boundary survey and may not include setting new corner markers. Ask up front what level of survey you’re paying for so you know what it covers.
Encroachments That May Affect the Transaction
An encroachment happens when something built on one property crosses onto another. It’s one of the most common problems a loan closing survey turns up. It can run in either direction, and both can cause trouble.
Typical examples include:
- A neighbor’s fence sitting a few feet inside your lot
- Your shed or carport crossing onto the neighbor’s land
- A driveway that clips the corner of the next parcel
- A roof overhang or porch that extends past the line
- A structure built on top of a utility or drainage easement
Encroachments matter because they can affect title coverage and loan approval. The title company may list the issue as an exception, which means the policy won’t cover problems tied to it. A lender may want it resolved before funding. Possible fixes include a written agreement with the neighbor, moving the structure, or another option your title company or attorney suggests. This article is general information, so get legal advice for your specific situation.
Access and Right-of-Way Issues a Survey Can Reveal
A survey shows how the property connects to a road, and that connection can be less clear than it looks. A right-of-way is a strip of land set aside for a road, sidewalk, or utilities. Legal access means you have a recorded right to reach your property, either by touching a public road or through a recorded easement.
Access problems often hide in plain sight. A lot may use a shared gravel drive that crosses a neighbor’s land with no recorded easement. A rural parcel may reach the road only by a path the prior owner used for years without written permission. Both can create headaches when you sell, refinance, or try to build.
The road right-of-way can also be wider than the pavement. Part of what feels like your front yard may sit inside it. That can affect where you place fences, landscaping, or a new driveway, so check the survey before planning work near the street.
How Building Locations Compare With Property Lines
A loan closing survey shows how far the house and other buildings sit from each property line. Those distances matter for more than curiosity. They tell you whether the home fits within local setback rules and how much room you have for future projects.
A setback is the minimum distance a building must stay from a property line. Local zoning sets these rules, and they can vary by municipality, zoning district, and lot type. Older homes may not match current setbacks because the rules changed after they were built. How that’s handled depends on local rules, so confirm with the planning office if it matters to your plans.
Many surveys also include a flood zone note based on the current flood map. That note can affect insurance costs and lender requirements. If the survey places any part of the home near a flood zone line, ask your lender what they’ll need from you.
When Survey Findings Require Further Review Before Closing
Some findings are minor and get noted without much fuss. Others need a closer look before anyone signs. Plan for extra review if the survey shows any of the following:
- A structure crossing a property line or sitting in an easement
- No clear legal access to a public road
- Gaps or overlaps with a neighboring parcel
- Differences between the survey and the deed description
- Buildings closer to a line than local setbacks seem to allow
Start by asking the surveyor to walk you through the concern. Then share it with your title company, agent, and lender so everyone knows what’s on the table. Legal questions about ownership or rights belong with a real estate attorney.
Timing makes all of this easier. Order the survey as early as your contract allows. Clearing up an encroachment or access question can take days or weeks, and a late survey leaves little room to act before your closing date.
