What Is a Mortgage Survey and Why Might Your Lender Ask for One?
You are working through a mortgage application, everything seems on track, and then your lender mentions a survey requirement. It can catch buyers off guard, especially if they thought the appraisal covered everything a lender needs to know. A mortgage survey does a different job. Understanding what it checks can help you move through closing with fewer surprises.
A mortgage survey is a property survey a lender asks for to confirm the physical details of a property before approving a home loan. It looks at boundaries, structures and site conditions that affect the property being used as collateral.
Warner Robins has grown steadily over the years. It has a mix of older neighborhoods and newer homes near the base and surrounding areas. Buyers here run into a range of property conditions. This is one reason lenders sometimes ask for a fresh mortgage survey instead of relying on an older one.
Why Lenders May Request a Mortgage Survey
A lender wants to feel sure that the property backing a loan matches its legal description and does not carry any hidden boundary problems. A mortgage survey gives them that proof through direct field checking.
Not every mortgage deal needs a new survey. Some lenders accept an existing survey if it is recent and still accurate. Others require a current one tied specifically to the loan. This depends on the lender, the loan type and sometimes the property itself.
Older or unusual properties, or ones without a clear past survey on file, are more likely to lead to a request for a new mortgage survey. If your property has features like additions, small buildings or a fence near the property line, expect your lender to pay closer attention to this step.
What Property Details a Mortgage Survey Documents
A mortgage survey records specific information about a property that a lender needs to review the loan. This goes beyond a simple measurement of the lot.
A mortgage survey usually records:
- The location of property boundary
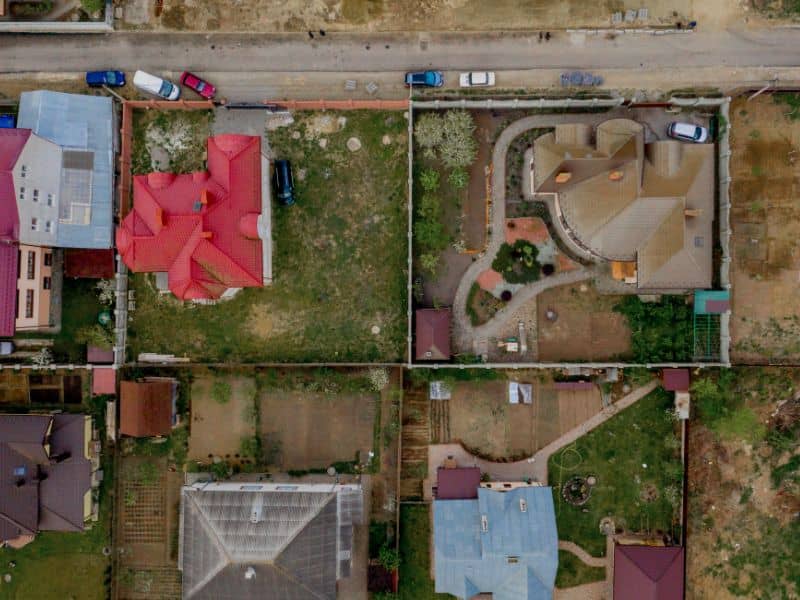
- Buildings, additions and other permanent structures
- Fences, driveways and other visible improvements
- Easements or rights-of-way crossing the property
- Any visible structures crossing onto or from neighboring properties
This information gives the lender a clear picture of exactly what is being financed, not just a guess based on the listing or the deed.
How Survey Information Supports the Lending Review
The property is the collateral behind a mortgage. A survey gives the lender documented proof of that collateral’s true condition, rather than relying only on paperwork.
During the lending review, an underwriter or loan officer looks at the survey alongside the appraisal, the title commitment and other closing papers. If the survey shows something unexpected, such as a shed built partly on a neighboring lot or an unknown easement, this can affect how the lender moves forward with the loan.
In an area, where property sizes and types vary from older in-town lots to larger properties on the outskirts, a mortgage survey helps a lender apply the same level of care no matter how a property looks on paper. This steady approach protects both the lender and the borrower from surprises after closing.
When Property Conditions May Require Additional Survey Work
Sometimes a standard mortgage survey turns up a condition that needs more attention before the loan can move forward. This does not automatically mean a dealbreaker, but it usually adds a step to the process.
Situations that can call for more survey work include:
- A structure that appears to cross a property line
- A fence or driveway that does not match the recorded boundary
- An unrecorded or unclear easement affecting the property
- A gap between the survey and the legal description in the title commitment
If your survey turns up one of these issues, your lender or title company will usually explain what needs to happen next. This can be a simple fix or something that takes more time, depending on the specific finding.
Coordinating the Mortgage Survey Before Loan Closing
Timing matters with a mortgage survey, since results can affect your closing schedule. Ordering the survey as early as possible in the loan process gives everyone involved time to review the findings and fix anything unexpected.
Confirm directly with your lender what type of survey they require and whether an existing survey might work. Requirements can be different by lender, loan type and property, so it is worth asking this question early instead of guessing.
Since a mortgage closing date is often tied to other deadlines, like a purchase contract or a rate lock, coordinating the survey early gives you the best chance of staying on schedule, even if the survey finds something that needs attention.
Frequently Asked Questions
Is a mortgage survey the same as an appraisal?
No. An appraisal estimates the property’s value. A mortgage survey confirms the physical boundaries, structures and site conditions of the property. Lenders may require both, but they do different jobs.
Do I need a new mortgage survey if I already have one from a previous purchase?
Not always. Some lenders accept an existing survey if it is recent and still shows current conditions. Ask your lender whether your existing survey will work or if a new one is required.
Who pays for the mortgage survey?
This is usually worked out as part of the loan and closing costs, and terms can be different by lender and transaction. Ask your lender how survey costs are handled for your specific loan.
